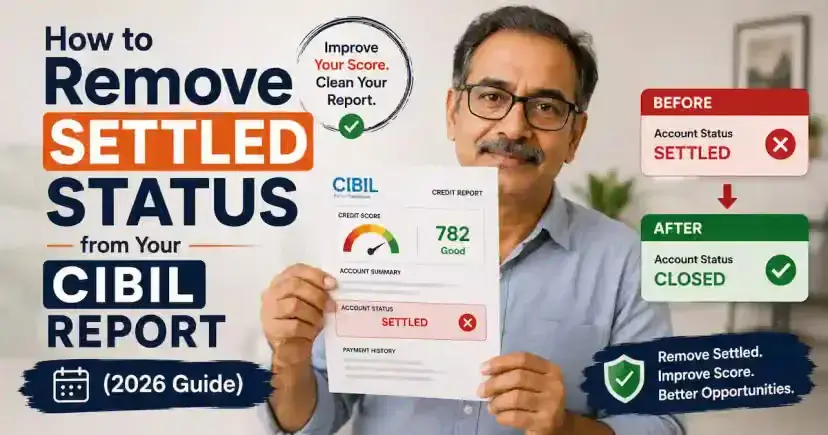
A “Settled” status on your CIBIL report can make it difficult to get a new loan or credit card. It usually means that a lender accepted a partial payment instead of the full outstanding amount.
The good news is that a settled account may sometimes be updated after you pay the remaining amount.
What Does “Settled” Mean?
When you settle a loan or credit card account, you generally pay less than the total amount originally owed. The lender then reports the account as “Settled” to the credit bureau.
This is different from a “Closed” account, where the full outstanding amount has been paid.
Can You Remove a Settled Status?
You usually cannot simply ask CIBIL to delete an accurate settled status.
However, if you later pay the remaining amount owed to the lender, you can ask the lender to review and update the account information.
The lender—not CIBIL—normally provides the account information that appears on your credit report.
Basic Steps
Contact the lender or credit card company.
Ask for the exact amount required to clear the remaining balance.
Pay the amount and keep the payment receipt.
Request a
No Dues Certificate
or other written confirmation from the lender.
Ask the lender to update the account status with CIBIL.
Check your credit report after the lender submits the update.
Important
Do not assume that paying an amount to a third party automatically changes your CIBIL status. Verify the payment process directly with the lender and keep all supporting documents.
What If the Status Is Incorrect?
If the account is already fully paid but your CIBIL report still shows “Settled,” you can raise a dispute with CIBIL and provide supporting documents.
However, the underlying lender may still need to confirm the correction before the bureau can update the information.
Final Takeaway
A settled account is not normally removed just because you contact CIBIL. The practical route is to work with the lender, clear any remaining amount where applicable, obtain written proof, and request that the lender update the account information.
Always check the updated credit report afterward to make sure the information has been corrected.
Spotted something on your own report that looks like this? Get a free review and we'll take an honest look.